

Signals: S1 Insurance Repricing · S5 Acute Climate Hazard · S4 Valuation & Appraisal Gap
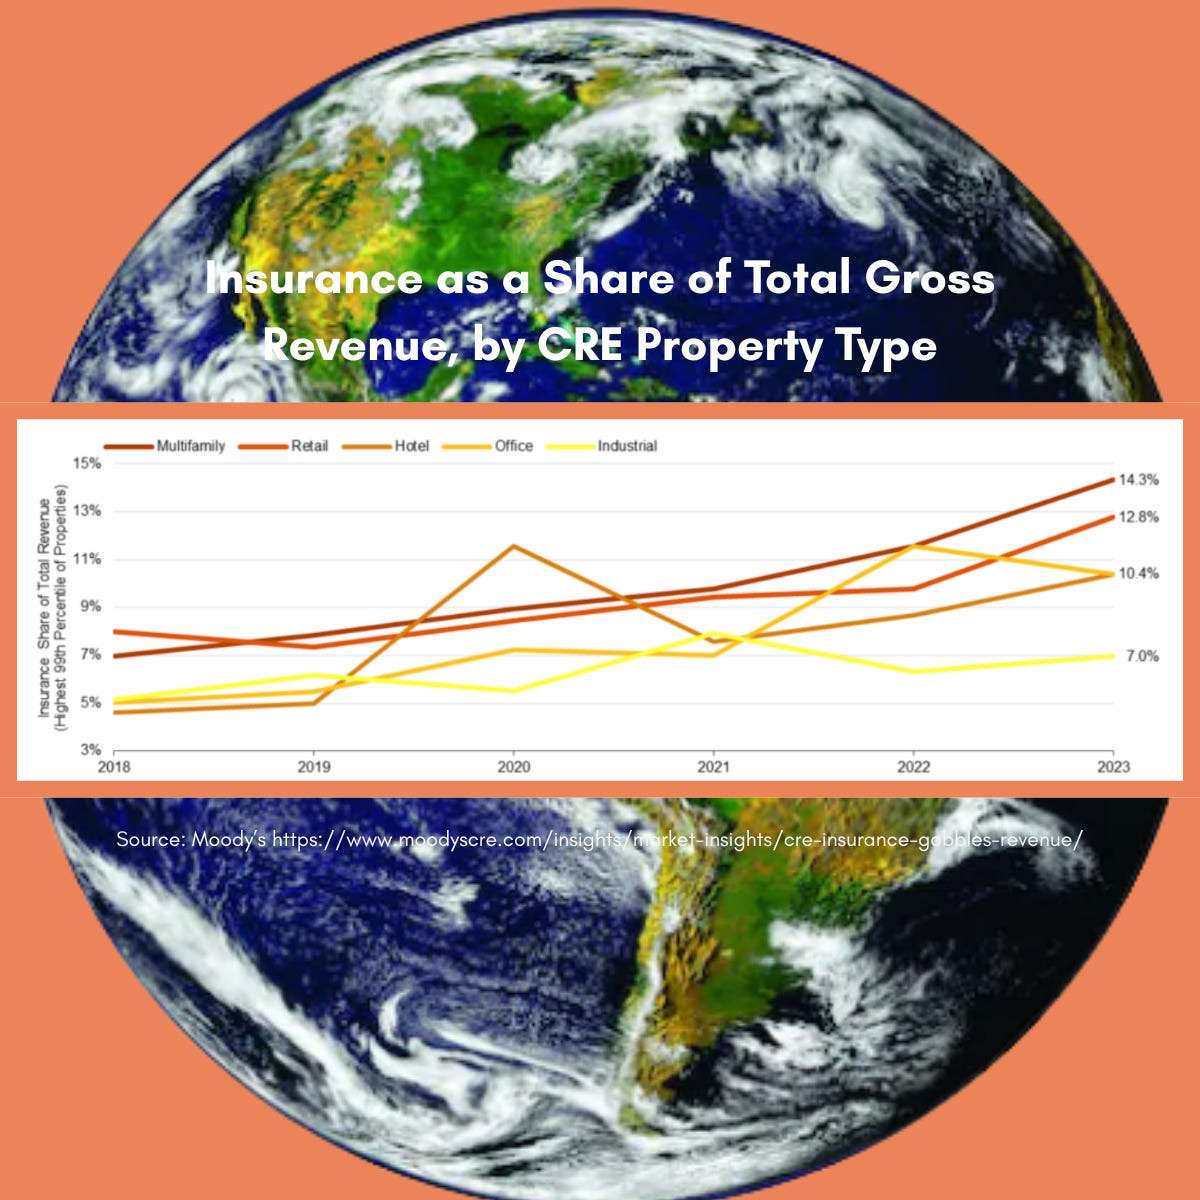
By Q3, 2024, insurance consumed 4.6% of property income in Orlando and 4.1% in Tampa. Note that MSCI’s denominator is income receivable (gross), not NOI. In Chicago, it is 1.3%. Those figures have not yet been updated. Per Insurify’s 2026 report, Florida residential homeowners insurance now averages $8,292 per year, a cost negatively impacting NOI, and one that is 181% above the $2,948 national average.
Nationally, insurance reached 2.4% of income receivable across MSCI’s US Quarterly Property Index, double its share five years earlier. JLL puts the increase in US commercial premiums at 88% over five years.
The same operating line item costs three and a half times as much in one market as another. The national share doubled over five years to Q3 2024, though rate increases decelerated through 2025.
That is not a cost problem. It is a geographic sorting mechanism operating on the largest asset class on earth.
Market Signal
Start with scale, because it explains why this matters beyond real estate.
Savills put the total value of global real estate, meaning residential, commercial, and agricultural land, at $393.3 trillion at the end of 2024. It is the world’s largest store of wealth. Nothing else in the investable universe carries that much capital, that much embedded social infrastructure, or that much long-duration dependence.
It is also, uniquely, immobile.
Equities reprice by reallocating. Real estate cannot escape its risk. It can only be repriced in place, which means the adjustment appears in the operating statement first, followed by the valuation.
That adjustment is now measurable. MSCI’s figure of 2.4% of income receivable is a national average, and averages conceal the mechanism. The mechanism is in the dispersion. Orlando at 4.6% and Tampa at 4.1%, against Chicago at 1.3%, is a spread of more than 300 basis points in income, applied every year, to assets that may otherwise be identical in quality and occupancy.
MSCI notes that climate exposure is not the only driver of that spread. Regulation and rebuilding costs contribute as well. That caveat belongs in any use of the data, and it does not weaken the point. Whatever the mix of causes, an owner in Tampa is surrendering three times as much of their income to insurance as an owner in Chicago, and that difference compounds into the cap rate.
The loss data behind it is worth understanding precisely, because this is where most climate commentary overstates and loses credibility with underwriters.
Swiss Re Institute put global insured natural catastrophe losses at $107 billion in 2025, with long-term real growth of 5% to 7% per year. Secondary perils, meaning wildfire, flood, and severe convective storms rather than headline hurricanes, accounted for 92% of 2025 insured losses, with severe convective storms alone at roughly $51 billion.
Swiss Re attributes more than 80% of the long-term rise in weather-related insured losses between 1970 and 2025 to exposure growth, meaning more development and higher asset values, rather than to climate signal.
If most of the rise comes from placing more valuable buildings in harm’s way, then the exposure decision is a portfolio-construction decision, and portfolio construction is something an allocator actually controls. Recognizing, of course, that just because a property that cost $30,000 when it was built and just sold for $1 million doesn’t make it “more valuable,” but it does reflect current replacement costs.
Case Study
The following is a modeled composite illustrating the transmission chain, benchmarked against the MSCI regional data above, with the roughly 2% starting point an assumption rather than a calibration or a specific transaction.
Picture an institutional investor in 2016 identifying a coastal metropolitan market with durable tourism demand and stable property values. They greenlight a full-service hospitality asset with conference space and ground-floor retail. The pro forma assumes stable insurance, continued coastal demand, and steady appreciation.
The building opens in 2020. Over the next five years, the building does not change. The location does not change. Near-term demand does not change - with the exception of weathering the pandemic.
What changes is the assessment.
Catastrophe modeling improves. FEMA maps update. Carriers re-examine surge history with better data. An asset that was insurable at standard rates in 2016 is now classified as high exposure.
The MSCI data roughly shows what that looks like in an operating statement. If the asset was underwritten when insurance ran around 2% of income, and it now sits at the Tampa level of 4.1%, the line item has roughly doubled as a share of income. In the most exposed submarkets within those metros, it runs higher still because a metro-level average smooths over differences in flood zones, construction types, and deductible structures.
Now watch the transmission. The lender sees the updated premium and recalculates debt service coverage. The asset becomes less attractive to traditional lenders. Refinancing gets harder. Some lenders withdraw from the market entirely. Others price the exposure into the spread. The cost of capital rises.
The building did not change. The location’s risk profile did. And in a levered asset, a change in the cost of capital is not a margin issue. It determines whether refinancing is possible at all.
The investor now has three options, and none of them are good. Refinance at a higher rate and accept a permanently thinner return. Hold and absorb the insurance cost by funding it from distributions. Or exit into a buyer pool that is pricing the same information.
Many choose to exit. When enough investors reach that conclusion in the same submarket, the exits themselves become the signal, valuations adjust, and the repricing that started as an insurance quote finishes as a comp.
Strategic Implications
The chain is short, and it runs in one direction. Physical risk becomes an insurance cost. Insurance cost becomes a financing constraint. Financing constraint becomes capital reallocation.
What makes it hard to act on is that each link has a different clock. Insurance reprices annually. Financing is repriced at refinance, which, for most assets, occurs once every five to seven years. Valuation reprices at sale, which may be once a decade. An owner can be three years into a repricing and still be looking at comps that describe the market before it started.
That lag is the actual risk, and it cuts both ways. It means an exposed asset can look fine for years. It also means the buyer who understands the insurance line before the comps catch up is buying with better information than the seller has.
The practical version of this is a single diligence habit.
When you evaluate a market, do not start with rent growth or cap rate. Start with insurance as a share of income, use the specific submarket rather than the metro, and compare it to the same metric from five years ago. If that ratio has doubled, you are looking at an asset whose returns are being redistributed to a carrier, and the comps haven’t priced it in yet.
For investors, portfolio durability now depends on which markets remain insurable, financeable, and desirable across a ten-to-thirty-year hold, not on which markets show the best trailing rent growth. Insurance as a share of income is the cleanest single proxy available, and MSCI publishes it.
For developers, site selection governs everything downstream, and it is made once. A location carrying a two-point yield premium in a resilient market can outperform a five-point yield premium in an exposed market over a twenty-year hold, because the exposed asset spends the back half of that hold paying for its location.
For suppliers and manufacturers, demand shifts toward anything an underwriter will recognize. That is a narrower category than “resilient products.” It means documented, third-party-verified performance, because carriers price evidence rather than intent.
For lending and proptech platforms, firms that can assess exposure at the parcel level during underwriting hold a real advantage in markets where conventional underwriting no longer describes the asset.
For municipal leaders, public infrastructure decisions directly govern the durability of private assets. Stormwater capacity, hardened utilities, and elevated substations protect private property value at a scale no individual owner can replicate. Cities that delay pay twice: once in adaptation costs that rise annually, and again in capital flight.
Future Signal
The forward number worth carrying is Deloitte’s projection that the average monthly cost to insure a commercial building rises from $2,726 in 2023 to $4,890 by 2030. That is a rise of about 80% within a single typical hold period, and it is a forecast rather than an observation, so treat it as a planning assumption rather than a fact.
The more structural change is methodological. The Grantham Research Institute assesses that climate is making insured hazards more severe, less predictable, and non-linear, which means historical claims data is becoming a weaker guide to future losses. Catastrophe models and property-level data have to fill that gap.
That has a direct consequence for owners. When carriers cannot rely on history, they rely on characteristics. Construction type, roof age and material, protection systems, elevation, distance to hazard. Which means the owner who can document those characteristics accurately gets priced on evidence, and the owner who cannot gets priced on the assumption that applies to their worst-case neighbor.
I expect the market to keep separating into two categories rather than declining uniformly. On one side, markets depend on temporary backstops like the National Flood Insurance Program and continued emergency infrastructure spending. On the other, markets are investing early in adaptation, with regulatory alignment among lenders, insurers,, and municipal authorities.
Capital moves methodically rather than suddenly, so this will not look like a crash. It will look like a persistent drift in where the marginal dollar goes, which, over three, five, and ten years, reshapes what gets developed, what gets financed, and what a market can charge in rent.
Brief 5 takes this from the asset class down to a single Sun Belt portfolio and shows what happens to a 9% IRR when you model the insurance line realistically.
As always, KNOW YOUR SIGNALS and BE CLIMATE READY!
Jamie
Run this on your own deal
The CRDF Signal Tracker™ built for this brief lets you log the insurance and capital-flow signals in your markets, translate them into financial impact, and score which ones are actually moving your pricing. Free, no signup: Brief 4 · CRDF Signal Tracker™ (xlsx)
New to the framework? The blank master Signal Tracker and Deal Stress Test workbooks are at climatereadyre.com/tools.
Related briefs
Same signal (S1 Insurance Repricing):
Brief 1 · Insurance Premium Hikes: Impact on Cap Rates & Property Value
Brief 8 · Office Overheating Risk and Valuation: What 40.3C Does to a Cap Rate - coming soon
Brief 11 · Hurricane Helene Aftermath: Western North Carolina Home Insurance Rates Rise 4.4% - coming soon
Next in sequence:
Brief 5 · Sun Belt Multifamily Insurance and IRR: Climate Risk Behind a 207% Rise - coming soon
Sources
Every figure above, with the date the data covers, the date it was published, and the date I verified it.
Global real estate value — $393.3 trillion, the world’s largest store of wealth.
Savills World Research — World’s real estate worth $393.3 trillion and is the world’s largest store of wealth · Data as of end-2024 · Published Sep 29, 2025 · Accessed Sep 2026
Florida property insurance average — $8,292 per year, 181% above the national average.
Insurify — Florida home insurance report · Data as of 2025 · Published Mar 2026 · Accessed Sep 2026
Insurify is a quote marketplace reporting its own data. Residential homeowners data, not commercial; 181% is $8,292 against Insurify’s $2,948 national average.
Insurance as a share of property income — 2.4% of income receivable nationally, double its share five years earlier; Orlando 4.6%, Tampa 4.1%, Chicago 1.3%.
MSCI — Insurance Has a Bigger Bite of Commercial-Property Income · Data as of 12 months to Q3 2024 · Published Dec 9, 2024 · Accessed Aug 2026
MSCI notes that regulation and rebuilding costs also contribute to the regional spread, not climate alone.
US commercial premium growth — 88% over five years.
JLL — How climate risks are impacting real estate insurance costs · Data period not specified by JLL · Published Jan 23, 2025 · Accessed Aug 2026
Global insured natural catastrophe losses — $107 billion in 2025; long-term real growth 5–7% per year; secondary perils 92% of 2025 insured losses; severe convective storms ~$51 billion.
Swiss Re Institute — Wildfires, storms, floods contribute to record 92% of global insured losses in 2025 · Data as of 2025 · Published Mar 19, 2026 · Accessed Sep 2026
Swiss Re Institute press release for sigma 1/2026.
Driver of long-term loss growth — Swiss Re attributes more than 80% of the 1970–2025 rise in weather-related insured losses to exposure growth rather than climate signal.
Swiss Re Institute — Wildfires, storms, floods contribute to record 92% of global insured losses in 2025 · Data as of 1970–2025 · Published Mar 19, 2026 · Accessed Sep 2026
Swiss Re Institute press release for Sigma 1/2026.
Predictability of insured hazards — climate making hazards more severe, less predictable and non-linear; historical claims a weaker guide, requiring catastrophe models and property-level data.
Retail Insight Network — Climate risk is changing the economics of retail property · Data as of 2026 · Published Aug 11, 2026 · Accessed Aug 2026
Secondary reporting of the Grantham Research Institute, LSE; primary publication not accessed directly.
Projected cost to insure a commercial building — average monthly cost rises from $2,726 in 2023 to $4,890 by 2030, a rise of about 80% (8.7% CAGR).
Deloitte Insights — The impact of climate change on commercial real estate insurance costs · Data as of 2023, projected to 2030 · Published May 29, 2024 · Accessed Sep 2026
A projection, not an observation. Cited to Deloitte directly rather than to secondary coverage.
Case study — coastal hospitality asset — modeled composite, not a specific transaction.
CRREI — modeled composite · Method: transmission chain illustrated at the MSCI-observed regional levels rather than at assumed percentages · Prepared for this brief, 2026 · Modeled — not a specific transaction
The ~2% starting point is an assumption, not a calibration; the surge asset is benchmarked to Tampa, with DSCR and refinancing consequences shown.
Commentary and analysis only. Not investment, financial, legal, tax, or professional advice. CRDF tools are illustrative; examples are composites drawn from public data. Do your own due diligence and consult qualified professionals.
I run this analysis on specific deals. If you are underwriting an asset in a coastal, wildfire, or water-stressed market and want the insurance and exit assumptions pressure-tested before you sign, book 20 minutes.
Jamie Wolf, MBA — Founder & Publisher, Climate-Ready Real Estate Investing, © 2026, CR REI Holdings LLC